Roof insurance claims in Mobile: documented, not argued
A hurricane claim in Mobile goes well when the damage is documented before anyone files, the adjuster sees everything, and the roof is built to the scope that's approved. It goes badly when a stranger in a truck promises a free roof. Here's how we do it, and what we won't do.
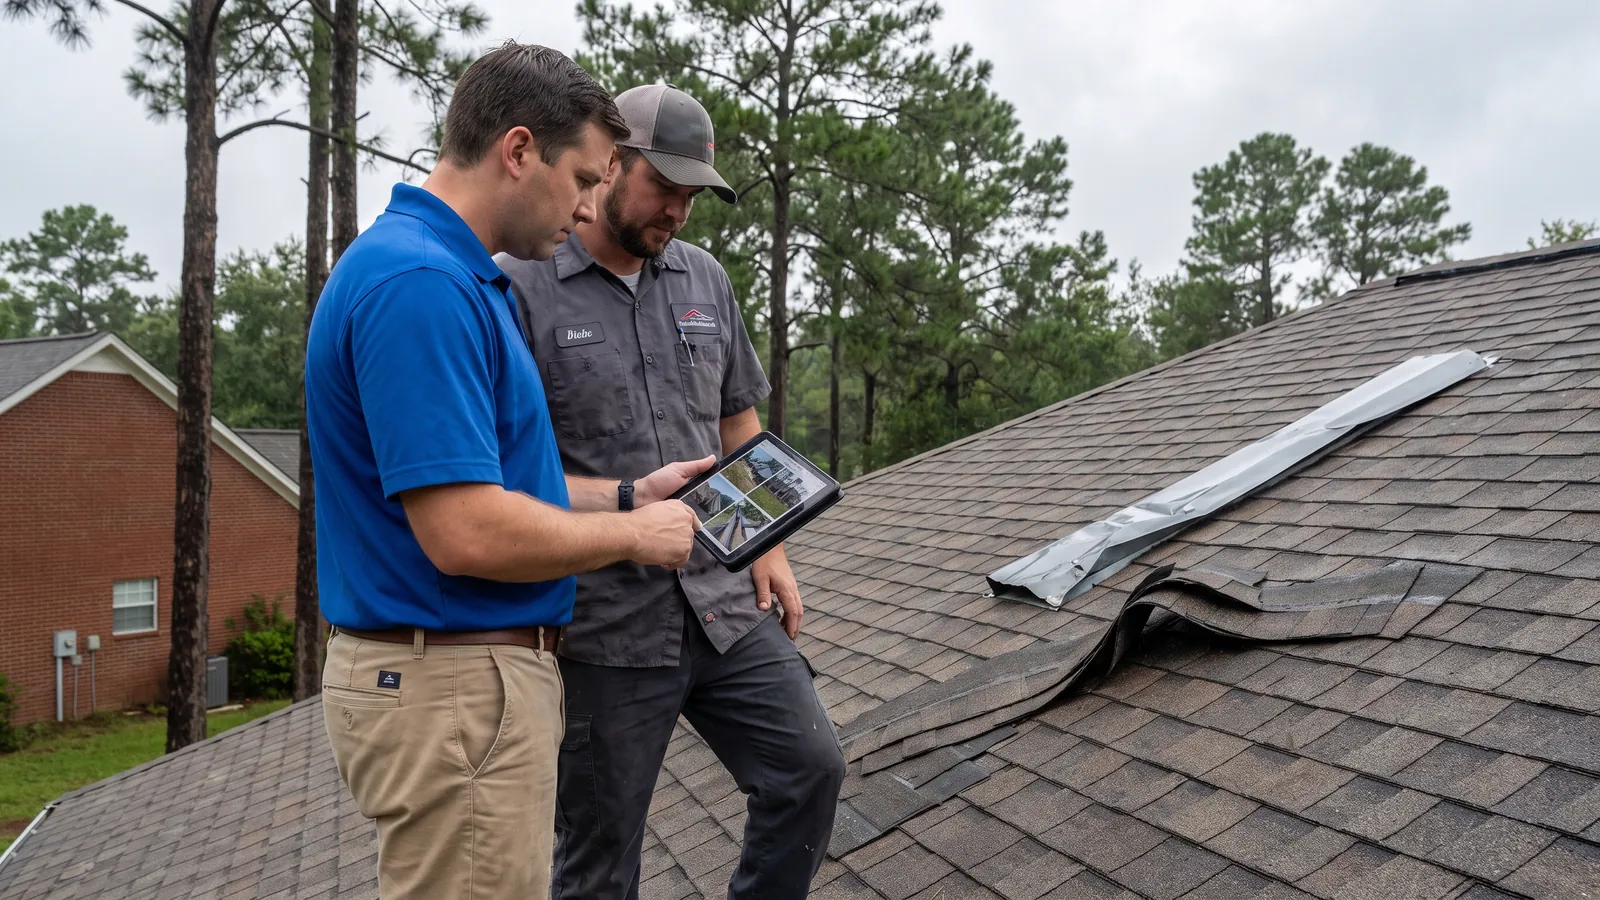
The order matters. Before you call your carrier, we get on the roof and photograph every slope, the ridge, the eaves, the vents and the flashing, measure the roof, pull the National Weather Service wind data for the storm date, and write an itemized estimate. That package, delivered to you, is what the adjuster works from, and it separates the storm damage (creased and lifted shingles, torn ridge caps, backed-out nails, a limb through the deck) from the wear the policy excludes (algae, granule loss, a roof already at the end of its life). On the coast your hurricane deductible is often a percentage of the dwelling coverage rather than a flat number, so the estimate also tells you whether a claim makes sense at all; sometimes a $1,400 repair on a policy with a $6,000 hurricane deductible is simply a repair, and we'll say so.
Then the adjuster. We meet them on the roof with the photos, walk the slopes together, and make sure the report covers what's actually there, including the hidden damage that doesn't leak until the November rains. If the carrier's scope misses something, we document it and you supplement; if the roof is a replacement, we build it to the approved scope and price, with the upgrades you want itemized separately. This is where the FORTIFIED pieces fit: a 2020 Alabama law made a FORTIFIED endorsement available on every homeowners policy, and most carriers' endorsements pay extra toward sealing the deck, ring-shank nailing and Class H shingles when a roof is replaced after a covered loss. Add the Strengthen Alabama Homes grant where a window is open and a storm-replaced roof can come out FORTIFIED for little or nothing beyond the deductible. See FORTIFIED roof and the grant and our guide to hurricane roof claims.
What we won't do. We don't waive, absorb or "work with you on" the deductible; that is insurance fraud, and Alabama's Home Builders Licensure Board issues the same consumer warning after every hurricane: check the roofer's credit-card-sized HBLB license card, verify it at hblb.alabama.gov or 334-242-2230, insist on written quotes and contracts (required by law), and get proof of workers' comp and liability rather than a promise. We don't act as a public adjuster or negotiate your claim; that's a licensed profession. We don't ask you to sign an assignment of benefits in the driveway. And we don't inflate a scope so the "free roof" pays for itself. After Sally, the crews that did those things were gone by Christmas, and their customers were left with roofs nobody would warranty.
What's included
Pre-filing documentation
Every slope photographed and dated, roof measured, NWS wind data pulled, itemized estimate written before you call your carrier.
Storm vs. wear, separated
The report shows what the storm did and what it didn't, so the adjuster conversation is about facts.
Adjuster walk-through
We meet the adjuster on the roof and show them the photos and the hidden damage.
Supplements documented
Anything the carrier's scope misses is photographed and written up for your supplement.
Built to the approved scope
Repair or replacement to the scope and price the carrier approves; upgrades itemized separately.
Endorsement and grant applied
FORTIFIED endorsement dollars and the Strengthen Alabama Homes grant used where you have them.
What a roof insurance claim costs you in Mobile, AL
| Job | Typical price | Notes |
|---|---|---|
| Storm inspection and claim documentation package | Free | Photos, measurements, wind data, estimate |
| Adjuster meeting on site | Free | Scheduled with your carrier |
| Emergency tarp (billed to the claim) | $300 – $1,100 | See emergency tarping |
| Wind-damage repairs to approved scope | $400 – $3,500 | One slope to several |
| Replacement to approved scope | $10,500 – $42,000 | Shingle to standing seam; see replacement |
| FORTIFIED upgrade on a claim replacement | + $1,500 – $2,500 | Often covered by the endorsement or the grant |
| Your hurricane deductible | Set by your policy | Paid by you, every time |
These are 2026 Mobile-area ranges so you can budget. Your written price is itemized (tear-off, decking, underlayment, sealed deck, flashing, vents, disposal, permit) and good for 30 days.
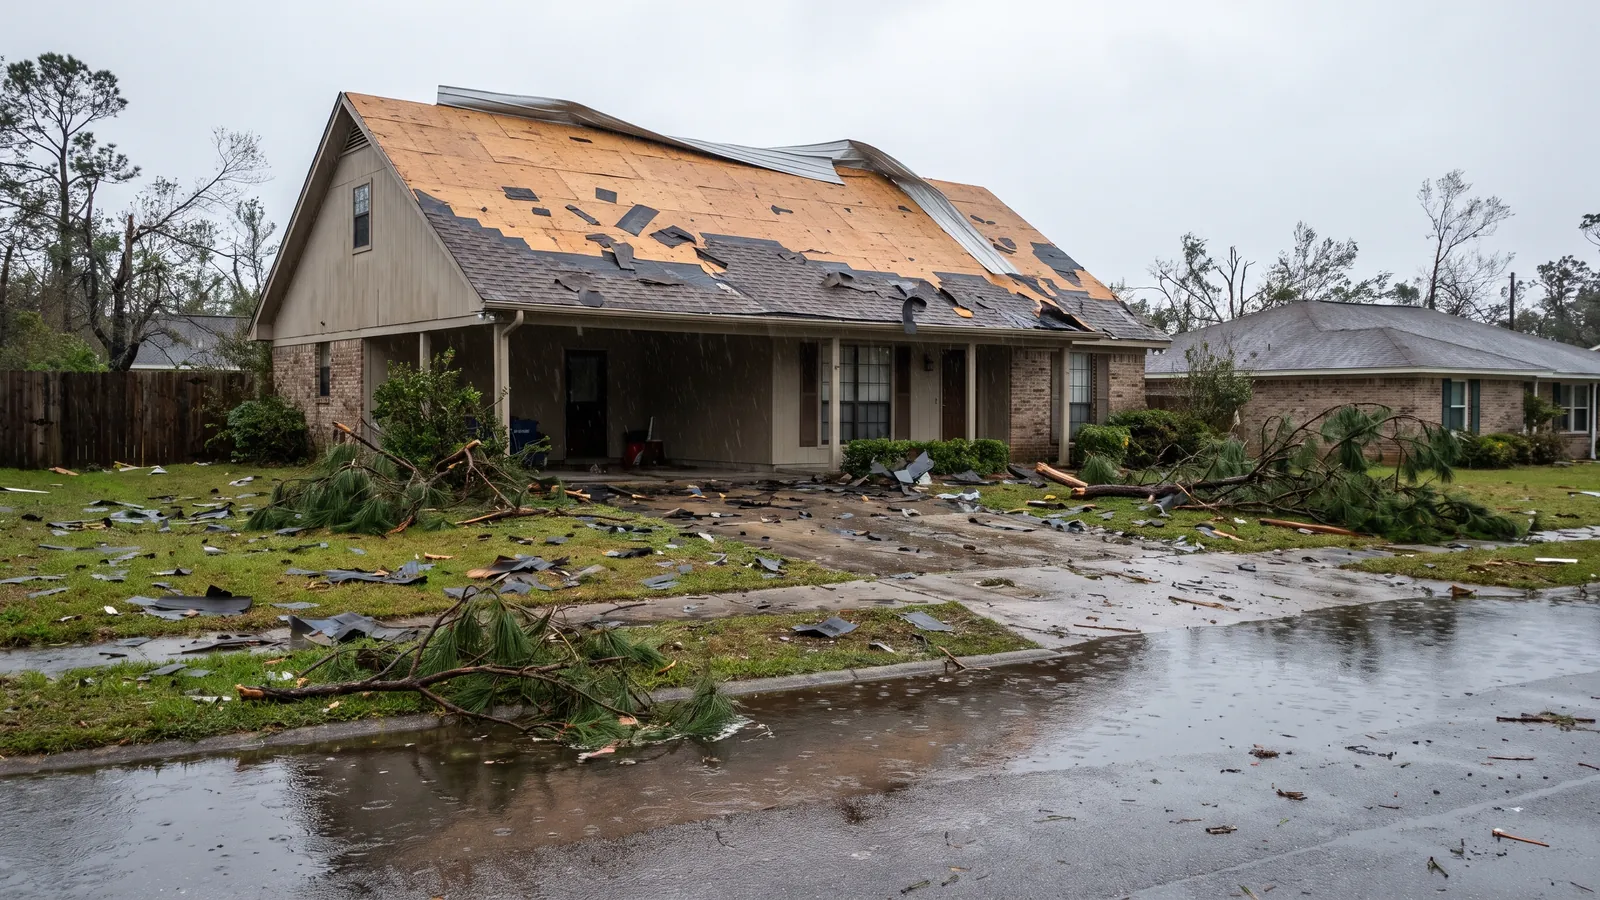
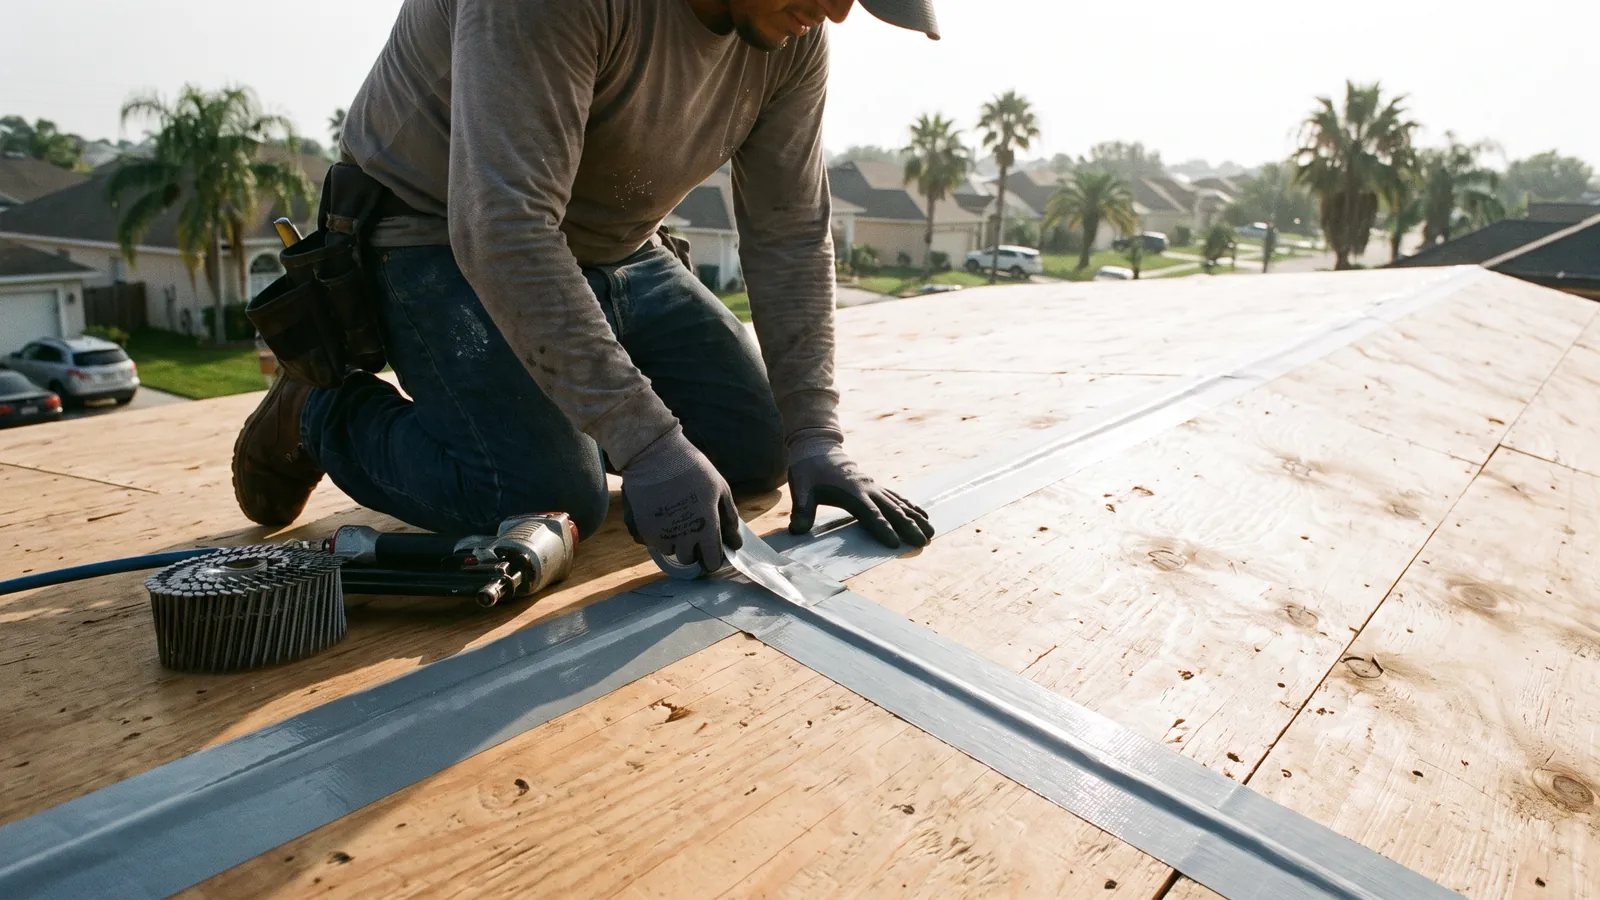
Recent work
Questions we get about insurance claims
Should I call my insurance company first or a roofer?
A roofer, for the inspection. If the damage is below your deductible or isn't storm damage, you've saved a claim on your record. If it is, you file with photos and an estimate already in hand.
What is a hurricane deductible?
A separate, usually higher deductible that applies to named-storm damage on most Gulf Coast policies, often 2 to 5 percent of your dwelling coverage. On a $300,000 house a 2 percent deductible is $6,000, which decides whether a repair is worth claiming.
Can you waive my deductible?
No. A contractor who offers to absorb or waive it is committing insurance fraud, and so is a homeowner who accepts. We itemize the deductible on the contract and you pay it.
The adjuster denied part of the damage. What now?
You can supplement with documentation. We photograph and write up anything the scope missed, and you submit it; carriers revise scopes on evidence all the time. If it stays denied, Alabama's Department of Insurance takes consumer complaints.
What is an assignment of benefits?
A document that signs your claim payments over to the contractor. Some are legitimate; most of the ones pushed in driveways after a storm aren't. Don't sign one until you've read it with the claim in front of you.
Can the claim replacement be FORTIFIED?
Usually, and it should be. The FORTIFIED endorsement on your policy pays toward the upgrade, the state grant covers up to $10,000 when a window is open, and the designation earns the discount Alabama law requires insurers to offer.